When you have several debts — credit cards, a medical bill, a personal loan — deciding which one to attack first can feel overwhelming. Two popular strategies dominate the advice: the debt snowball and the debt avalanche. Both work. They just work differently, and choosing the right one for your personality can be the difference between becoming debt-free and giving up halfway.
This guide explains how each method works, compares their costs with a realistic example, and helps you pick the one you will actually stick with.
How the Debt Snowball Works
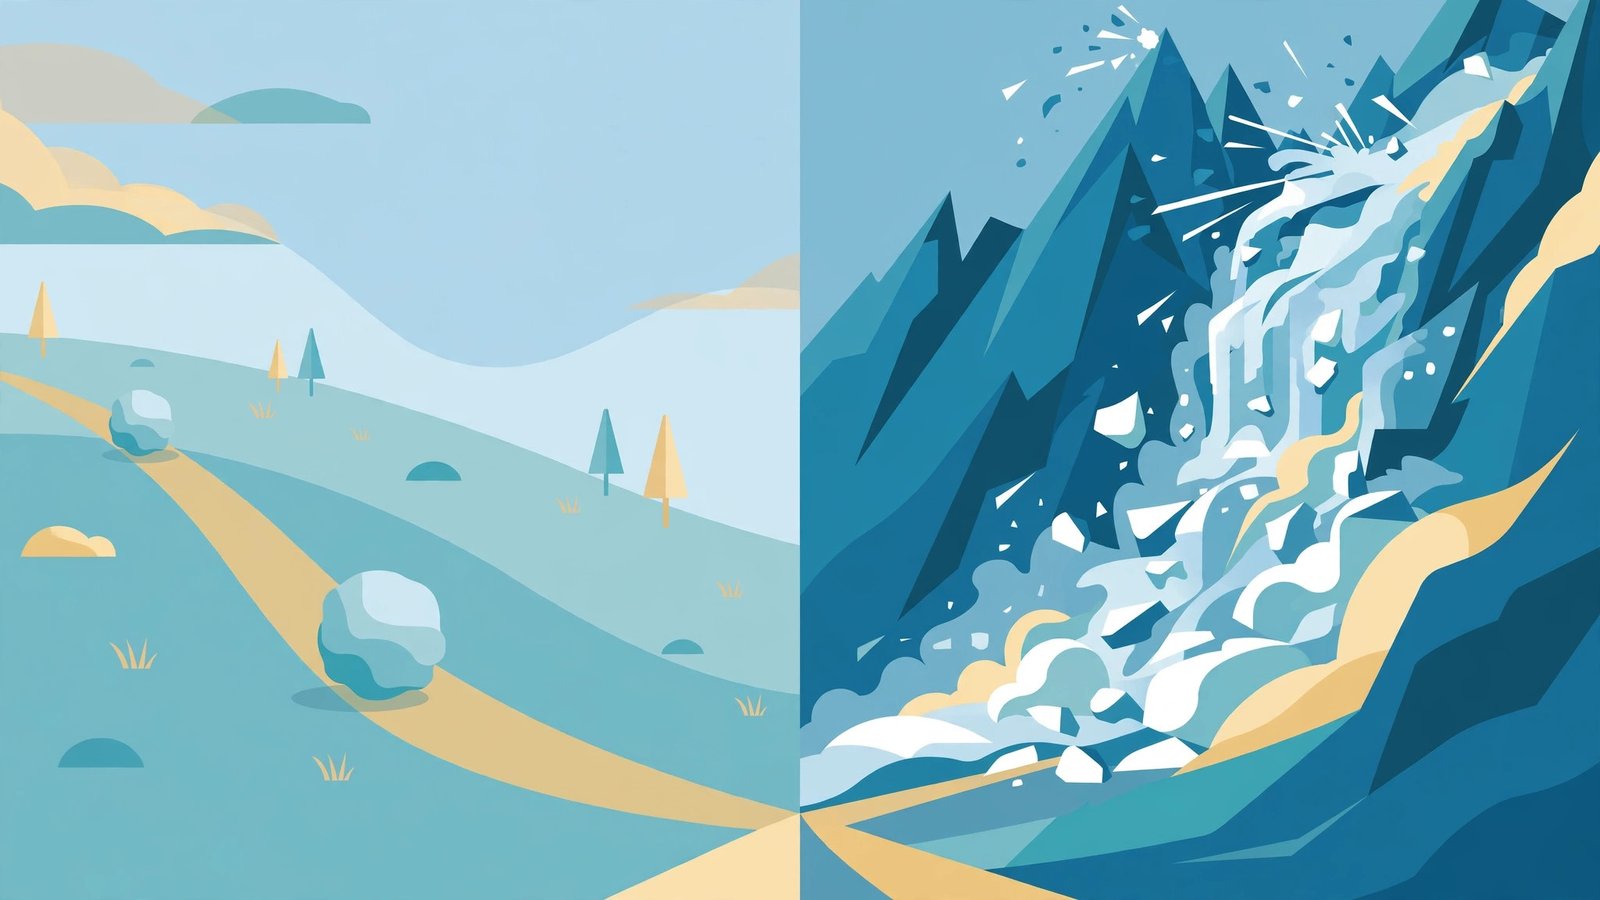
The debt snowball focuses on balances, from smallest to largest. You list all your debts, make minimum payments on every one, and throw all your extra money at the smallest balance first. When that debt is gone, you roll its payment into the next-smallest debt — like a snowball growing as it rolls downhill.
Snowball Example
Imagine three debts:
- Store credit card: $600 balance
- Medical bill: $1,800 balance
- Credit card: $4,500 balance
With the snowball, you attack the $600 store card first, regardless of its interest rate. Once it is paid off, you take the money you were paying on it and add it to the minimum payment on the $1,800 medical bill. When that is gone, everything rolls into the $4,500 card.
The appeal is psychological: you get your first "win" fast. Paying off an entire debt — even a small one — feels like real progress, and that feeling keeps you motivated for the long haul.
How the Debt Avalanche Works
The debt avalanche focuses on interest rates, from highest to lowest. You make minimum payments on everything and direct all extra money at the debt with the highest interest rate first. Once it is gone, you move to the next-highest rate.
Avalanche Example
Using the same three debts, suppose the rates are:
- Store credit card: $600 at 24% APR
- Credit card: $4,500 at 21% APR
- Medical bill: $1,800 at 0% (payment plan)
With the avalanche, you attack the 24% store card first, then the 21% credit card, and finally the interest-free medical bill. Because you kill the most expensive debt first, you pay less total interest over time.
The appeal is mathematical: this method minimizes the total amount you pay. Every dollar goes where it saves you the most money.
Snowball vs Avalanche: Head-to-Head Comparison
Total Cost
The avalanche wins on pure math. By targeting high-interest debt first, you pay less interest overall. The gap is small when your debts have similar rates, but it can be substantial when one debt carries a much higher rate than the others. If minimizing cost is your top priority, the avalanche is the logical choice.
Speed of First Win
The snowball usually delivers a paid-off debt faster, because small balances clear quickly. If motivation is your weak point — if you have started payoff plans before and quit — that early win matters more than a small interest saving.
Simplicity
Both are simple, but the snowball has a slight edge: balances are easy to see and understand, while interest rates sometimes require digging through statements. That said, either method fits on a single sheet of paper.
Psychological Fit
This is where the real decision happens. Personal finance is personal. Studies on debt payoff behavior have found that people who focus on small wins tend to stick with their plans longer and pay off more debt overall. The math-favoring avalanche only saves money if you follow through — and many people find it discouraging to hammer away for months at a large high-interest balance with no debt fully disappearing.
Which Method Should You Choose?
Choose the snowball if:
- You have quit debt plans before and need momentum
- You have several small debts that could be cleared in a few months
- Your interest rates are all fairly similar, so the extra cost is small
- Seeing debts disappear keeps you motivated
Choose the avalanche if:
- You are disciplined and motivated by saving money, not by quick wins
- One debt has a much higher interest rate than the others
- You have a large balance at a high rate that is costing you serious interest
- You want the mathematically optimal path and will stick with it
The Honest Answer
The "better" method is the one you finish. An avalanche plan you abandon after three months costs far more than a snowball plan you complete. Be honest with yourself about what keeps you going. There is no prize for choosing the mathematically perfect method if you do not follow through.
How to Get Started With Either Method
- List every debt. Write down the balance, interest rate, and minimum payment for each one. Do not skip any — store cards, medical bills, personal loans, all of it.
- Sort your list. Smallest balance first for the snowball; highest rate first for the avalanche.
- Set your budget. Find your extra payment amount — the money beyond minimums you can put toward debt each month. Be realistic so you do not burn out.
- Automate minimums. Set up automatic minimum payments on all debts so nothing slips and triggers late fees.
- Attack the top of the list. Direct all extra money at the first debt on your list until it is gone, then roll the payment to the next.
- Track your progress. A simple chart or spreadsheet showing balances dropping over time is powerful motivation.
Mistakes That Sabotage Either Method
- Taking on new debt while paying off old debt. This is the number one payoff killer. Put the credit cards away — literally — while you work the plan.
- Skipping the emergency cushion. Without even a small emergency fund, every surprise becomes new debt. Build a small starter fund first if you can.
- Ignoring the budget. Extra payments have to come from somewhere. If your budget is fiction, your payoff plan is fiction too.
- Refinancing without a plan. Balance transfers and consolidation loans can lower your interest rate, but they only help if you stop adding new debt and keep making payments.
Can You Combine the Two?
Yes. Many people use a hybrid: knock out one or two tiny debts first for the psychological win, then switch to the avalanche for the remaining balances. This is a perfectly reasonable approach — the best plan is one designed around your own behavior.
FAQ
Which is better: debt snowball or debt avalanche?
The avalanche saves more money in interest; the snowball delivers faster early wins and may be easier to stick with. The better method is the one you will actually complete. If you have quit payoff plans before, try the snowball. If you are disciplined and one debt has a much higher rate, try the avalanche.
How much more does the snowball cost compared to the avalanche?
It depends on your balances and rates. When rates are similar across debts, the difference is often small — sometimes just a few dozen dollars. When one debt has a much higher rate, the gap can be hundreds or thousands of dollars. List your debts with their rates to see how big the difference is in your case.
How long does it take to pay off debt with these methods?
It depends on your total debt and how much extra you can pay each month. A useful habit: calculate your debt-free date when you start, using your planned extra payment, and revisit it monthly. Seeing the date move closer is strong motivation with either method.
Should I build an emergency fund before paying off debt?
A small starter fund of around $500 to $1,000 is wise before aggressive payoff. Without it, every emergency becomes new debt and undoes your progress. Keep making minimum payments on all debts while you build that cushion.
Does the debt snowball or avalanche help my credit score?
Both can help over time. Paying down balances lowers your credit utilization ratio, which supports your score, and a history of on-time payments builds positive history. The method matters less than consistent payments and shrinking balances.
This content is for general educational purposes only and is not professional financial advice.